AVOL
Definition / Formula
After-hours traded volume as a percentage of the average regular-hours session volume. Both use the New York clock, for crypto and TradFi rows alike.
AVOL = sum(volume, 16:05 to 20:00 ET) / ADV_RTH * 100
ADV_RTH = mean(regular-hours session volume over the last 21 sessions)
          (20 on the weekend calendar)
Regular hours: 09:30 to 16:00 ET. Today’s session enters the average only once it is complete.
Window: New York local minutes 965 to 1199, that is 16:05 to 19:55 inclusive. The 16:00 closing print is excluded.
Day attributed: the current session day once the last bar is at or after 16:05 ET, otherwise the most recent earlier session day. A New York day outside the calendar is never attributed: on Monday between 00:00 UTC and the New York midnight, New York is still on Sunday evening, so the cell shows Friday’s after-hours. The tooltip names the date.
Pre-market is excluded from this column; it is tracked separately because it overlaps the London session.
Not populated when no complete New York regular-hours session is stored, or while a TradFi instrument is closed for the weekend.
UI Breakdown
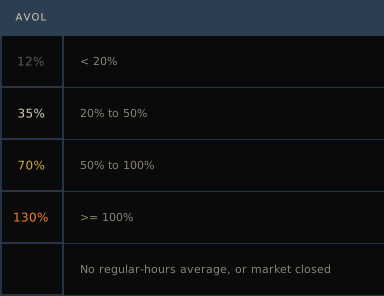
Centred text, rounded to a whole percent. The colour is selected by band on the unrounded value, so 19.6% reads 20% and stays dimmed.
| Control | Action | Effect |
|---|---|---|
| Column header | click | sort descending (largest first); click again to flip |
Value Ranges
| See | Value Band | Status | Visual Appearance |
|---|---|---|---|
 | < 20% | Below the reporting floor | Dimmed text |
 | 20% to 50% | Standard | Standard text |
 | 50% to 100% | Elevated | Gold text |
 | >= 100% | Above a full regular-hours day | Orange text |
 | No regular-hours average, or market closed | No after-hours value | Empty cell |
Summary: AVOL reports after-hours volume as a percentage of the instrument 21-day regular-hours average.